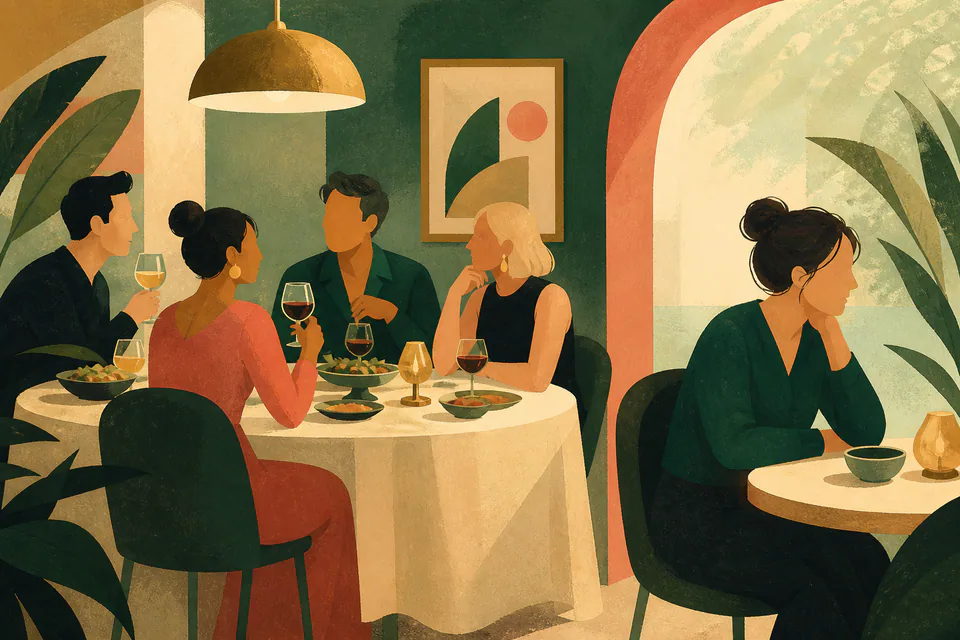Listen through the publisher, then discuss the episode here or arrange an in-person Roundtable. Your city determines where to meet.
Roundtables are designed for groups of four, with a shared subject and room for everyone to speak. Come for discussion, with no dating expectation.
About 1 in 5 homeowners under 35 in Canada got at least part of their down payment as a gift. If your kid later splits up, whether your gift stays theirs depends on the province. In Ontario it's generally shared once it goes into the family home. In BC and Alberta it's usually still theirs, with the growth shared. Quebec has its own rules, and common law changes things again. What I'd do: 1. Decide if it's a gift or a loan, and paper it that way. 2. Put the gift in your kid's name alone if that matters to you. 3. Keep the trail: the transfer, the statement and the letter. 4. A marriage contract or cohabitation agreement lets the couple set their own rules. 5. Make sure your own retirement doesn't still need that money. More at calmmoneycoach.com I'm not a lawyer. Talk to a family lawyer in your province before the money moves. Rules as of 2026.
Episode information is provided by the publisher. Listening takes place on the publisher’s service.
In this Jim Rohn Motivation video, Jim delivers a masterclass on the power of journaling and how it can shape your personal development, mindset, and future success. ️ Don’t let the ideas slip away—capture them, grow from them, and let them guide your journey. Key Topics From This Motivational Video: The critical difference between a diary and a journal Why journaling sharpens memory, clarity, and self-awareness How to use your journal to design your future and track progress Journaling as a tool for leadership, discipline, and accountability How your journal becomes a legacy for future generations This video dives deep into Jim Rohn's personal story of transformation through journaling, and offers timeless advice on how to make your thoughts tangible, your goals real, and your future intentional. Learn how writing things down changes not just what you remember—but who you become. This Jim Rohn Motivational Video Is Perfect For: Anyone struggling with clarity or direction in life Aspir
Sometimes the people who need comfort end up giving it. In this deeply tender conversation, Sage Robbins connects with Linda, a woman navigating one of life's hardest seasons as she cares for her father, who has dementia. As Linda shares the qualities she sees in others and recognizes in herself: kindness, strength, perseverance, humor, generosity, the two women discover they are walking the very same path. Sage's own mother is in memory care, and what unfolds is a mirror of shared grief, grace, and love. Uploaded 04-10-26 Watch more videos like this “Husband Left, Mom Was Dying, I Had a Miscarriage” (All in One Month) | Jillian Turecki: https://youtu.be/G3QqRTasx2o I Was Humiliated… And It Made Me Who I Am: https://youtu.be/-YDXWSJ-gu0 The One Question That Changed My Marriage: “How Am I Being?": https://youtu.be/3o3pvEAJu_U I Couldn't Carry a Baby for 20 Years (What Finally Changed Everything): https://youtu.be/LtFFxH5DFLQ Join my weekly newsletter 'The Mirror' to receive these exclu
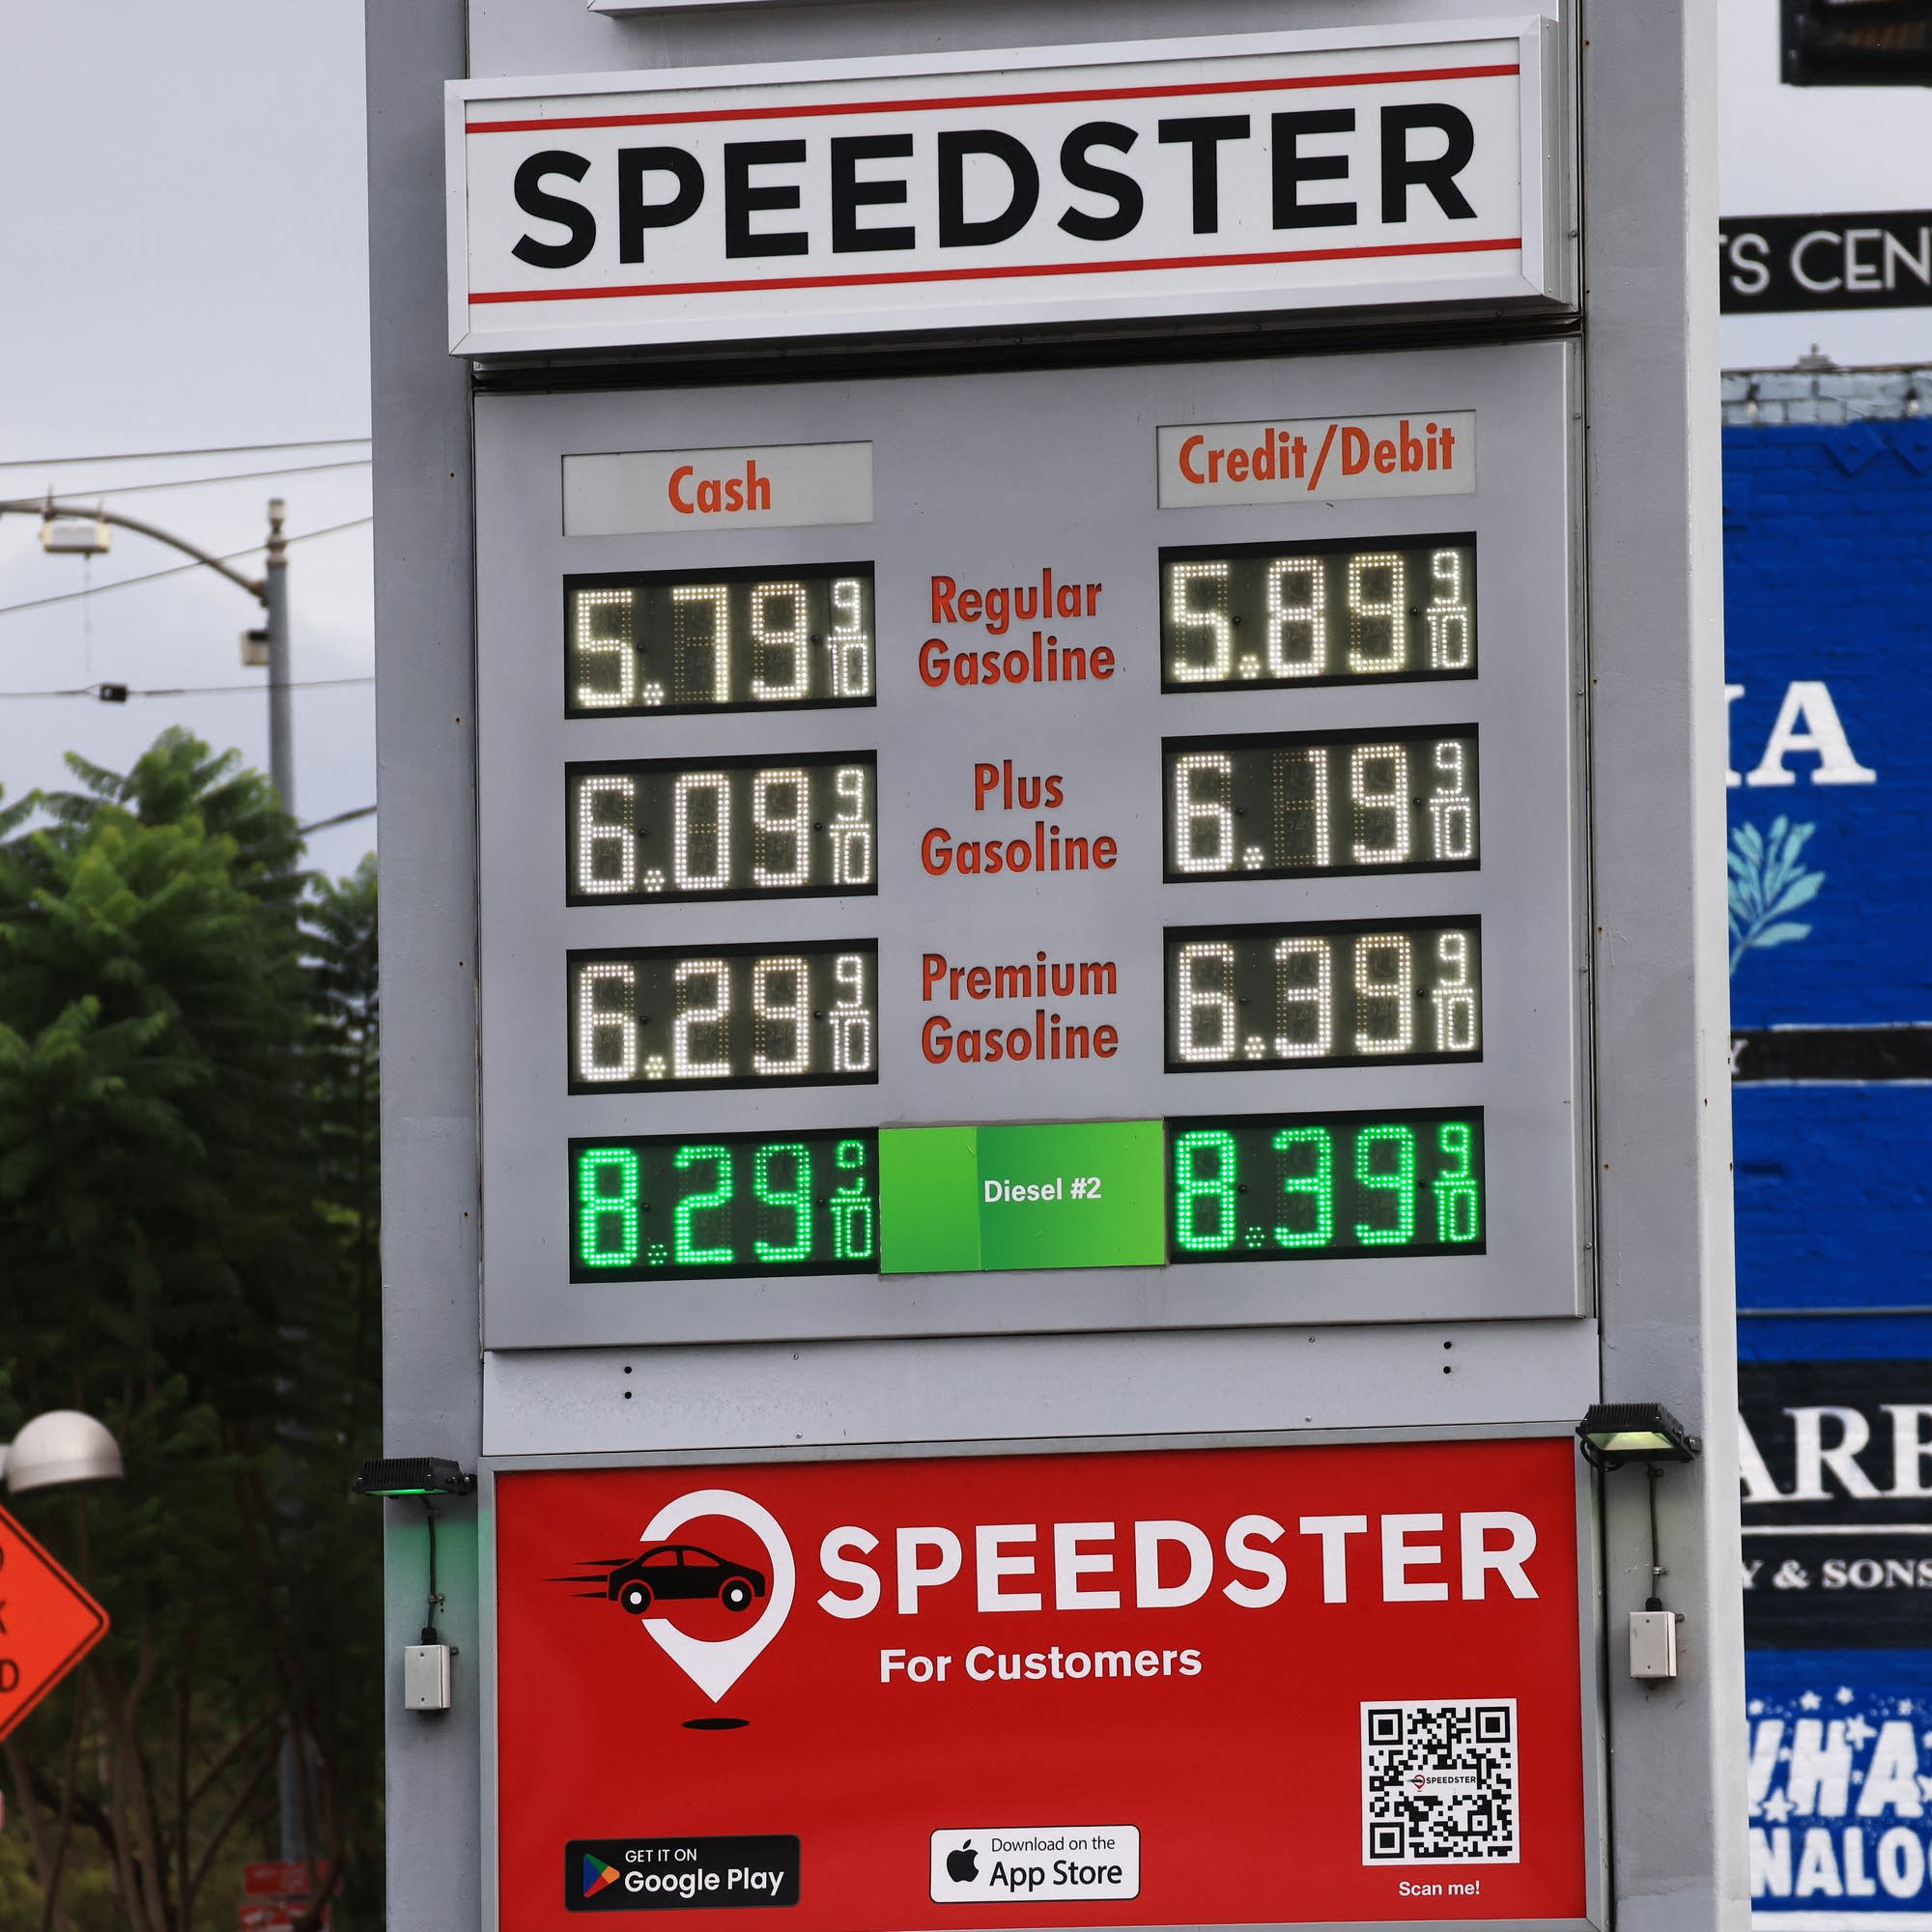
Economists use “core” inflation to describe price changes minus food and energy (which can be up one week and down the next). But for the past six months, energy prices have been stubbornly high, as the White House drags out its war in Iran. That sustained inflation is having a trickle-down impact. In this episode, why core inflation can’t escape fuel costs. Plus: Retailers cater to picky consumers, and the stock market tumbles after a historic IPO. Every story has an economic angle. Want some in your inbox? Marketplace is more than a radio show. Read the stories in today’s episode: Who wants more oil? (https://www.marketplace.org/story/2026/11/20/trump-xi-and-putin-meet-in-china-plus-anthropics-ipo) Core inflation measures can't escape high energy prices (https://www.marketplace.org/story/2026/11/20/core-inflation-measures-cant-escape-high-energy-prices) Salmon may soon be off the menu as fisheries struggle to meet demand (https://www.marketplace.org/story/2026/11/20/salmon-supply-flo
Someone experienced gives you a confident recommendation. The relief is immediate. Can you explain why the advice fits your life, or only who told you to follow it? In this episode of The Level Up Podcast, Paul Alex breaks down how to learn from a mentor while staying responsible for understanding your own decision. Relevant experience can reveal mistakes you have not learned to recognize. Paul emphasizes that respect for someone’s success still leaves you with a responsibility to connect the guidance to your circumstances. Ask what the recommendation depends on and what could make it less useful. Those questions can deepen understanding without becoming an argument. Before committing your time or resources, explain the choice in your own words so you know what you are applying and can recognize when conditions change. In this episode, you’ll learn: • Why a mentor’s experience does not remove your responsibility to understand. • Which questions help connect guidance to your actual circ
November 20, 2026: Melissa Lee and the Fast Money traders unpack a brutal market sell-off, NVIDIA’s latest concerns, what's next for Anthropic, Bitcoin’s break below $59,000, and whether healthcare can still offer shelter. The key takeaway: traders see possible near-term bounces, but they remain cautious about unresolved risks in AI, rates, credit, and market leadership. Hosted by Simplecast, an AdsWizz company.
Is selling Bitcoin now a smart move or the biggest crypto mistake? Today, we break down Bitcoin price predictions, market trends, and the latest crypto news to uncover what could be next for BTC. Plus, we cover top altcoin opportunities and what Bitcoin's next move could mean for the entire crypto market! Trade at Bitbase - https://www.bitbase.com/en/accounts/invite/jwpe3h Join Skool Community - https://www.skool.com/discovercrypto/about Trade wtih Toobit- https://www.toobit.com/activities/c/tradingdashdc ●▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬▬● All of our contents are strictly personal opinions. Please make sure to do your own research. Never take one person's opinion for financial guidance. Our contents ARE NOT financial advice. Our contents are sponsored & include affiliate content. Only use exchanges for trading digital assets. We never keep our entire portfolio on an exchange. #bitcoin #crypto
Month 1 as an executor comes down to 1 rule. Nothing leaves. The money, the car and her ring all stay put while you protect things and write them down. My free Executor Kit has the whole first 30 days checklist and a workbook, with who to call in your province. Get it at calmmoneycoach.com. General education for Canadians. Takeaways 1. Giving away keepsakes can count as accepting the executor job, so photograph first and decide after. 2. Keep her phone and mail going. The security codes and statements lead you to her accounts. 3. Many banks pay the funeral invoice straight from her account. Her credit card debt gets paid from the estate. The family only owes it if it was joint or co-signed. 4. Call her home insurer this week. Many treat a home as vacant after about 30 days. 5. Hold off paying out the estate until the CRA clearance certificate comes. I'm Brian Orlando, CPA, in Halifax. Advice-only planning through Calm Money Coach. No products, no commissions.
Over the last 10 years, about 99 out of 100 Canadian stock picking funds did worse than the plain Canadian market they were trying to beat. You can own the whole world stock market in 1 fund, for about $200 a year on $100,000. It's called an all in one ETF, and yes, the tickers sound like Wi-Fi passwords. I go through the story and the research behind it, a Nobel Prize argument, Warren Buffett's $1 million bet and a bit of caveman psychology, so you understand why the simple path works and can stick with it. I'm a Canadian accountant and planner, and I don't sell any of this. My free Keep It Simple tool walks through it step by step at calmmoneycoach.com. General education for Canadians. 2026 figures. Takeaways 1. Money you need in the next few years stays in cash or a GIC. 2. Winners are hard to spot ahead of time, for pros and whole countries. Own them all. 3. Keep the cost low, under about 0.25 percent. 4. Pick the mix you'd hold through a drop of half. 5. Pay yourself first, automa
There are 6 main ways to turn your savings into a retirement paycheque in Canada: stay invested and sell a little each year, live off dividends, buy an annuity, keep a few years in cash, a glide path, or a GIC ladder. I ran Gord and Anne, both 65 with $800,000 saved, through each one in my planner. None of them is wrong and each trades something. The all GIC plan that feels the safest was the one most likely to run out. Where I'd start: 1. Your floor from CPP and OAS. 2. Do you want it guaranteed or in the market, options open or locked in? 3. Run your real numbers through a bad start. 4. Decide now what you'd trim in a bad year. 5. Spend some of it. Plus where I lean with my own money. And yes, the federal budget proposes letting your RRSP stay open past 71. The minimum withdrawals would still start at 72. More at calmmoneycoach.com Ontario example, 2026.
Access to effective legal representation should not depend mainly on personal wealth.
Share your view, then see how readers voted. No sign-in required. This poll is shared across stories.
Do you agree or disagree?
Common Quandary
A Common Quandary to discuss
Another conversation to explore, separate from this news story.
One friend is rich, one is broke, and everyone ordered differently. How do you split dinner?
A group of longtime friends traditionally divides restaurant bills equally. Their incomes have grown increasingly unequal, and one friend now declines gatherings because even their share is difficult to afford while others order without thinking about price.
When should friendship adjust for differences in wealth?