How to prepare financially for a layoff in your 50s
14 min
Listen through the publisher, then discuss the episode here or arrange an in-person Roundtable. Your city determines where to meet.
Roundtables are designed for groups of four, with a shared subject and room for everyone to speak. Come for discussion, with no dating expectation.
1064. What should you do with your retirement contributions when a layoff looms in your mid-50s? Host Laura Adams tackles a listener’s question about building a cash cushion without sacrificing growth for retirement. Whether you're navigating late-career volatility or job insecurity as a younger worker, these tips will help protect your financial future. Key Takeaways Even with a looming layoff, try to contribute at least enough to capture your full employer match to a retirement account, giving you a guaranteed 100% return. For emergency funds you may need within the next year, prioritize savings in an FDIC-insured high-yield savings account. Leaving your job in or after the calendar year you reach age 55 waives the 10% early withdrawal penalty on your current employer's retirement plan. Distributions from traditional retirement accounts remain subject to ordinary income tax no matter your age. While the rule of 55 eliminates the 10% penalty, you must have owned a Roth plan for at least five years for the pre-tax earnings to be tax-free. Sole earners supporting family members should have at least six months of essential living expenses saved as a cash reserve. Older job seekers should modernize resumes by trimming them to the last 10 to 15 years of experience, removing graduation dates, highlighting quantifiable business results, and showcasing proficiency in enterprise platforms, popular tools, and AI workflows. Discover more from Money Girl! Facebook (https://www.facebook.com/MoneyGirlQDT) Hosted on Acast.
Episode information is provided by the publisher. Listening takes place on the publisher’s service.
The Five Pillars of Financial Freedom | Jim Rohn Motivation True financial freedom isn’t just about money—it’s about building the habits, mindset, and principles that create lasting wealth. In this powerful Jim Rohn motivational video, you’ll discover the five essential pillars of financial success that can help you create security, opportunity, and independence. Uploaded 05-10-25 Jim Rohn explains that wealth is not something you chase—it’s something you attract by becoming a disciplined, responsible, and growth-minded individual. These five pillars will show you how to manage your money wisely, invest in yourself, and build a financial foundation that supports the life you want. In this video, you’ll learn: The five pillars of financial freedom and how to apply them. Why discipline is more important than income when building wealth. How to create multiple streams of income for financial security. Why financial freedom starts with self-education and personal growth. Practical steps to
Uploaded 04-05-25 Are you ready for the AI revolution—or will you get left behind? Tony Robbins breaks down what it really takes to thrive in a world that's changing faster than ever. We're talking AI, robotics, nanotech—disruption at a scale humanity’s never seen before. ---- Tony Robbins AI is a fully interactive experience powered by the proven tools and wisdom of the world’s #1 life and business strategist. It’s like having Tony Robbins as your personal guide, available anytime you need support...in your native language! Get the first 14 days of Tony Robbins AI access for $1 when you subscribe today! Learn more about Tony Robbins AI here: https://tonyr.co/4lSeobA Watch more videos like this "AI Is Changing Healthcare Forever" - Marc Andreessen, Ben Horowitz: https://youtu.be/lqb14Cb17M0 Jordan Peterson - "Most People Learn This TOO LATE In Life": https://youtu.be/6fwrTb3dm5Y 3 Skills You NEED to Prepare Yourself for What's Coming: https://youtu.be/K-jOtLM9c7o The World Is Changing
On 4th March 2023, UN member states agreed a historic treaty that had been over fifteen years in the making. The High Seas Treaty is the first ever treaty to protect the world’s oceans outside national boundaries. The aim is to meet the 30 by 30 biodiversity target, protecting 30% of the world’s oceans by the year 2030. Also known as the open sea or international waters, the high seas begin at the limit of countries’ exclusive economic zones. That means up to 370km, or 200 nautical miles, from the coastline. They account for 64% of the world’s oceans, and have been referred to as the last true wilderness, given how much mystery still lies within. Why is protecting the oceans so important? What measures are expected to come from the treaty? In under 3 minutes, we answer your questions! To listen to the last episodes, you can click here: How to make the most out of a rental property? (https://originals.bababam.com/do-you-really-know/202303090400-how-make-most-out-rental-property) What is
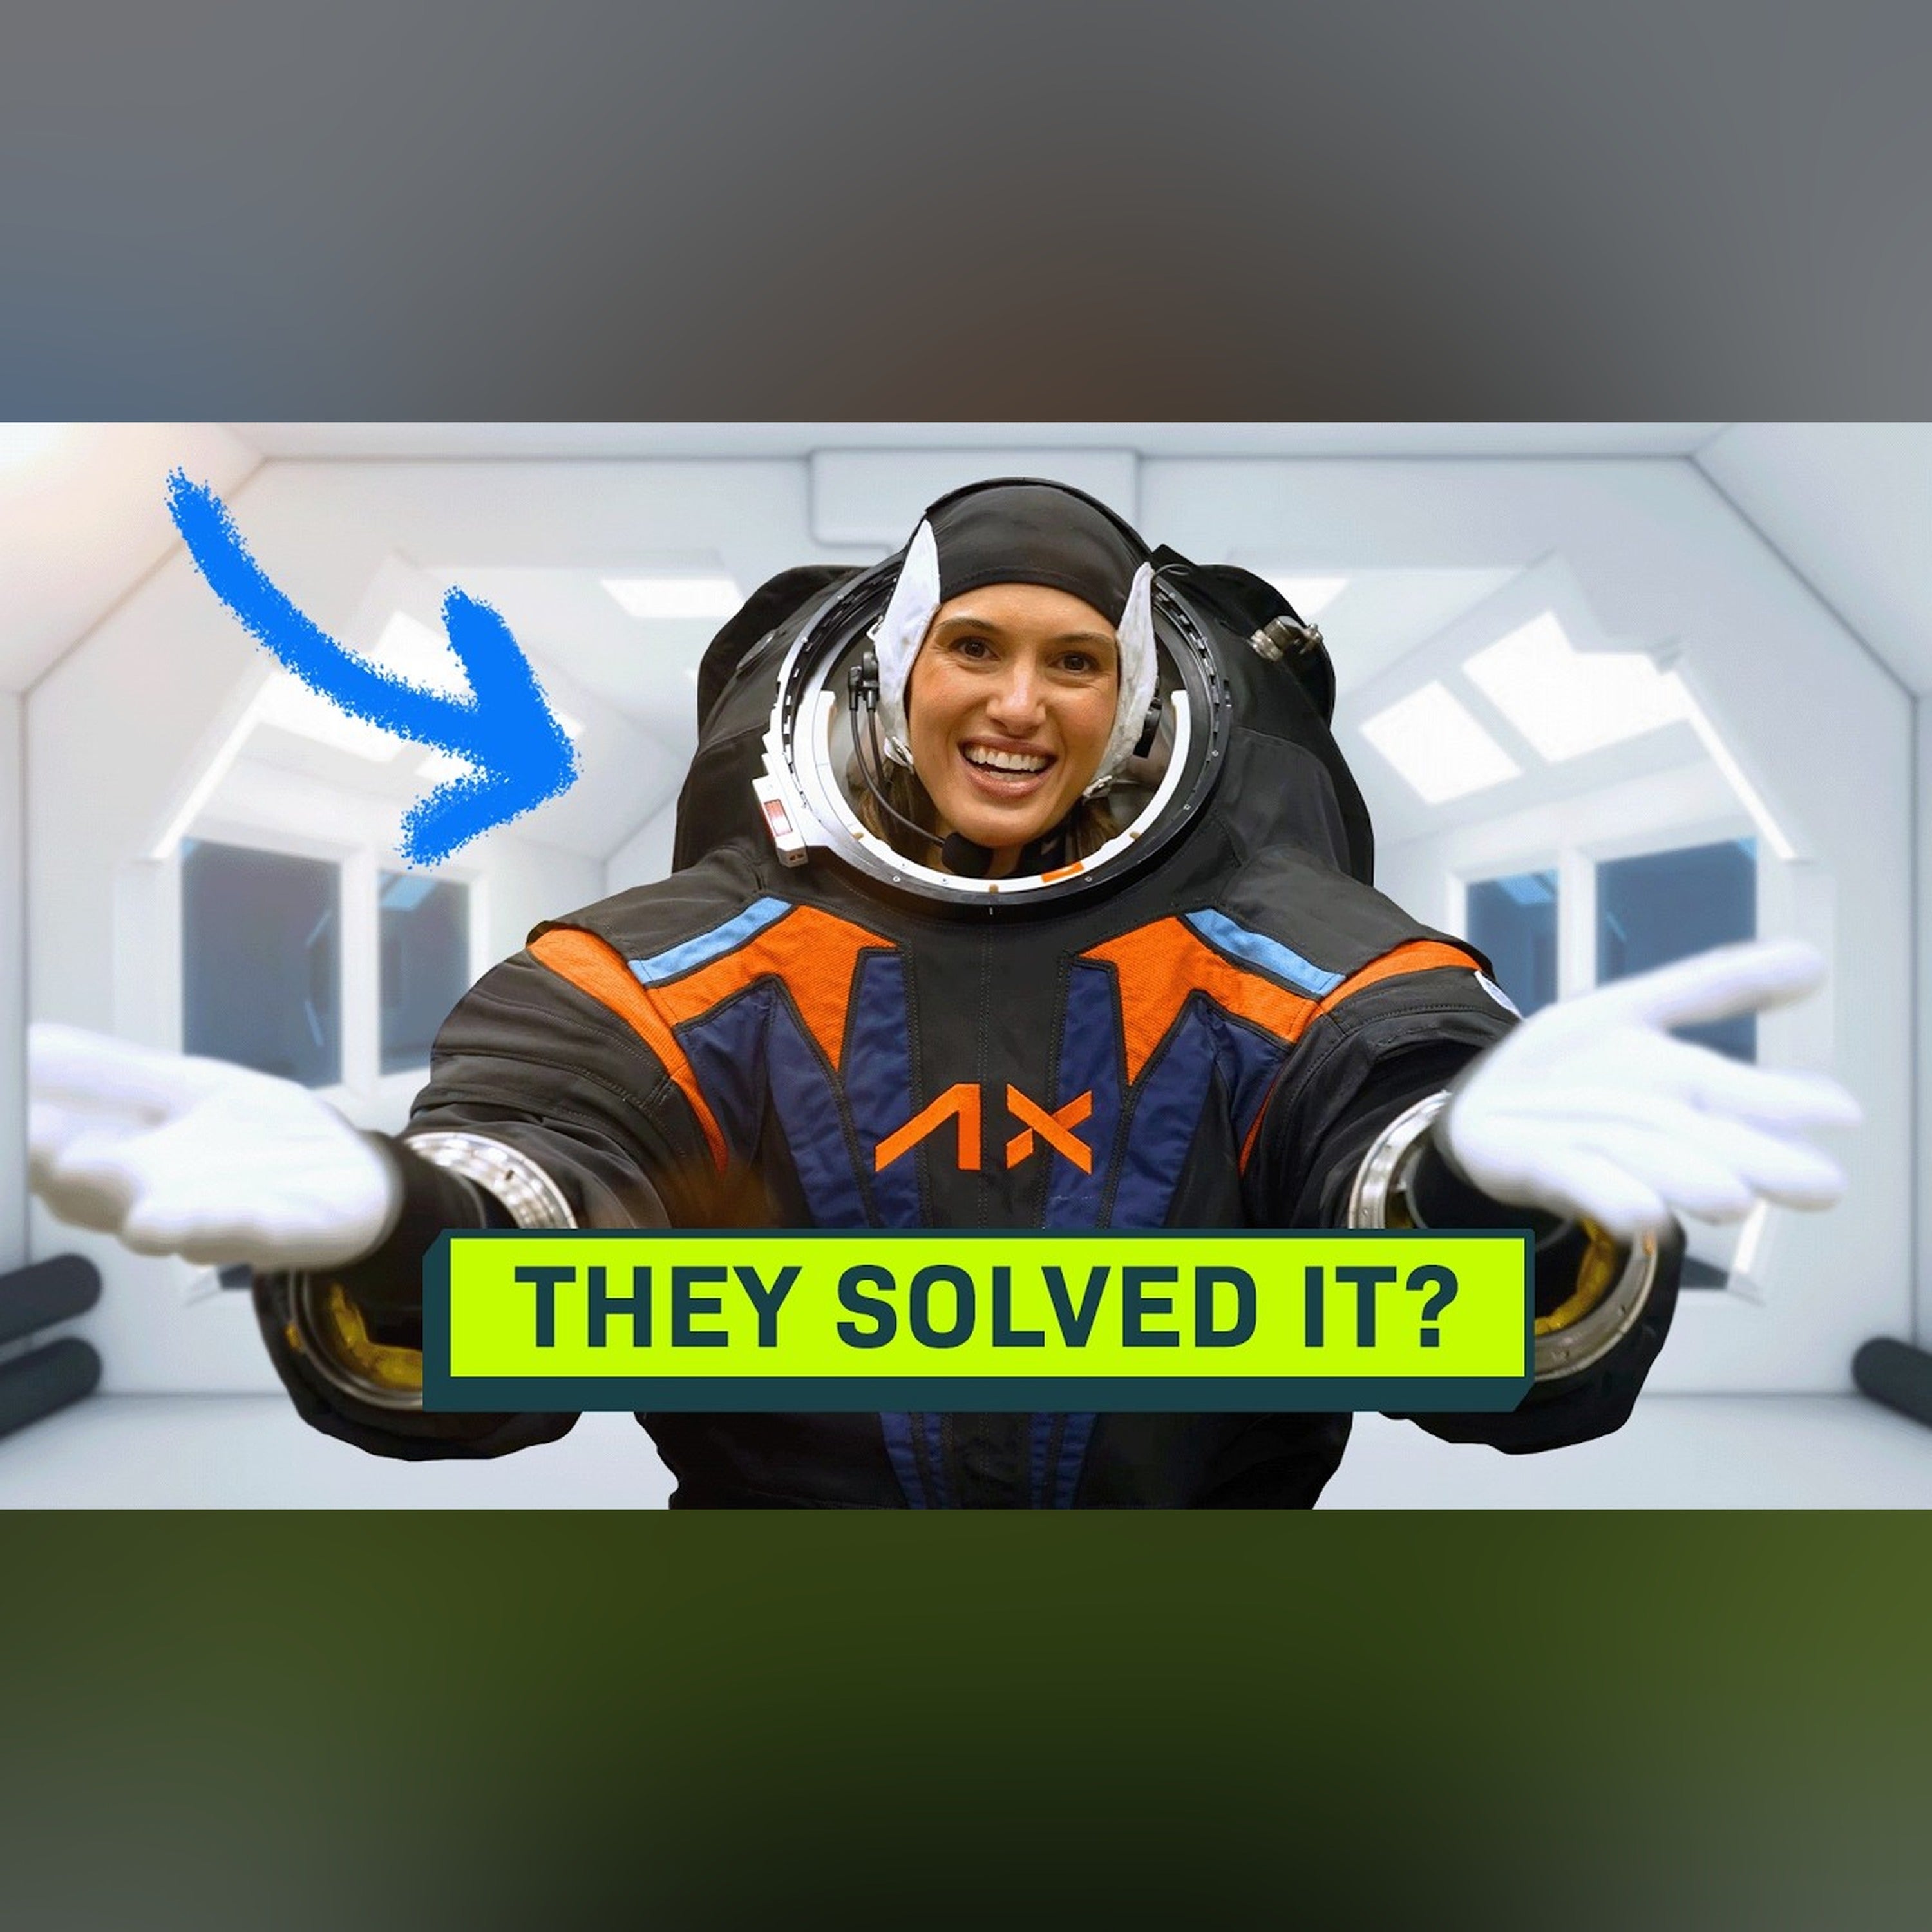
This will be the next space suit on the moon. What can it do? Only 12 people have ever walked on the moon and they all did it within just 4 years of each other. Then, for the last 50 years, no one has gone back… but that’s about to change. Soon, astronauts will return to the moon to prepare for people to live there long-term and to get us ready to send the first humans to Mars. But to do it, they need to survive outside in space and work for hours in one of the most dangerous conditions a human will ever face. The problem is, our spacesuits for the Moon haven’t been updated in decades! But now, to make this next chapter in space possible, space suits are getting a major upgrade. These new suits will give astronauts the superpower to do more, for longer… and I’m one of the first civilians to put one on. In this video, we’re taking you behind the scenes to show how Axiom Space is designing, building, and testing NASA’s new space suits. I am going to put myself and this suit to the test,
An optional overtime shift opens up and you automatically say yes. What is that time buying? The income and the hours you trade both deserve a clear purpose. In this episode of The Level Up Podcast, Paul Alex breaks down how to evaluate a genuinely optional extra shift against your needs, goals, and available time. Paul reflects on long law enforcement weeks and wanting greater control over his time. The episode distinguishes a real choice from required work or income needed for essentials, then asks what the next additional shift serves. There may be a strong reason to take it. Name that reason and consider what the hours would otherwise support, including recovery, a personal commitment, or learning. A deliberate comparison can help you decide without assuming that either money or time should always win. In this episode, you’ll learn: • Why required hours and essential income change the context of the decision. • How to identify the specific need or goal an optional shift serves. • W
Get the 200+ Page Optimal Living Daily Workbook (PDF) - Free. Want to turn today's episode into an actionable plan? Episode 3779: Joshua Fields Millburn and Ryan Nicodemus of The Minimalists explain the first steps they took to regain control of their money after years of six-figure debt. It starts with a written monthly budget that sorts every expense into essentials, nonessentials and junk, plus a small safety net for emergencies, and then reframes investing as simply paying your future self, automated so you never miss the money. Read along with the original article(s) here: https://www.theminimalists.com/freedom/ Quotes to ponder: "Most of us have no idea where our money is going. We think we know, but we don't really know." "The stricter you are, the sooner you'll be free." "Right now is the best time to start planning for your future." Airwallex is a financial technology company, not a bank. Services in the US are provided by Airwallex US, LLC, a licensed money transmitter (NMLS
1067. Auto insurance rates have become one of the most expensive items in a typical household budget. If you haven’t reviewed your policy or shopped around in years, you may be overpaying. Host Laura Adams explains how to review your policy and see if you can pay less without sacrificing coverage. You’ll get a guide for shopping, comparing, and switching auto policies like a pro. Key Takeaways Compare insurance using your current policy’s declarations page before requesting quotes so you can match exact liability limits, deductibles, and endorsements. State auto insurance minimums are often too low and leave your personal savings exposed in a serious crash. Consider purchasing at least 100/300/100 liability coverage plus uninsured/underinsured motorist protection, and a personal umbrella policy if you have significant assets. If the combined annual cost of collision and comprehensive coverage exceeds 10% of your car’s current market value minus your deductible, consider dropping those
1066. Do you have high-interest credit card debt? Host Laura Adams answers a listener’s question about how balance transfers work and compare with personal consolidation loans. You'll learn how both options affect your credit scores and ways to slash thousands in interest while keeping monthly payments manageable. Key Takeaways A 0% APR balance transfer temporarily pauses interest, allowing you to avoid monthly finance charges and save money. Balance transfers typically charge a fee, such as 3% to 5% of your balance, which gets added directly to your account. Once a balance transfer promotion expires, any remaining balance resets to the account’s standard APR, which could be 24% to 29%+. Missing a minimum payment on a balance transfer can void the low or 0% promotional rate and trigger a penalty APR up to 29.99%. A personal loan that pays off higher-rate debt costs more in total interest than a balance transfer you pay off before the promotional rate expires, but can have a lower month
1065. But did you know an HSA has more tax benefits than a Roth IRA and a traditional 401(k) combined? Host Laura Adams breaks down the perks and how to build more retirement wealth with an HSA. You’ll learn the "shoebox strategy," what happens to funds after 65, and traps to avoid. Key Takeaways HSAs offer pre-tax contributions, tax-free investment growth, and tax-free withdrawals for qualified medical expenses. The "shoebox strategy" allows you to reimburse yourself tax-free for qualified healthcare expenses at any time. You can choose to pay healthcare expenses out-of-pocket and let an HSA balance grow, with no spending deadline. At age 65, the 20% non-qualified withdrawal penalty disappears, which makes an HSA similar to a traditional IRA where distributions are taxed as ordinary income. Enrolling in Medicare past age 65 automatically backdates your coverage by up to six months, which can trigger a 6% penalty on HSA contributions. Discover more from Money Girl! Facebook (https://ww
Platforms should explain their content-removal decisions using publicly available rules.
Share your view, then see how readers voted. No sign-in required. This poll is shared across stories.
Do you agree or disagree?
Common Quandary
A Common Quandary to discuss
Another conversation to explore, separate from this news story.
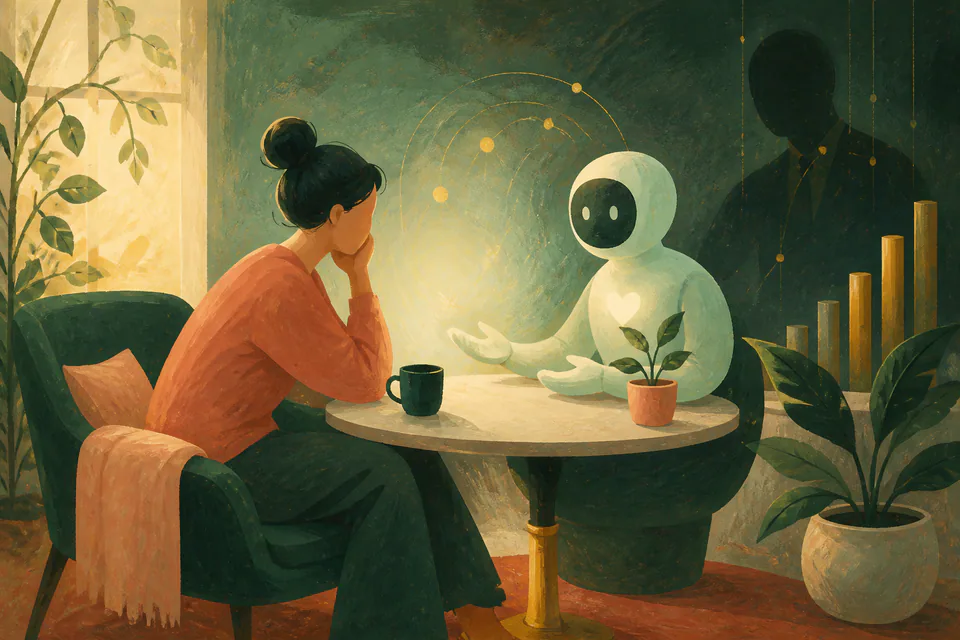
Your best friend is an AI that profits when you stay lonely. Is the friendship real?
A lonely adult considers an AI companion their closest confidant. The service is always patient and supportive, but the company profits when users spend more time engaged with it.
Does a comforting system have a duty to make itself less necessary?