Listen through the publisher, then discuss the episode here or arrange an in-person Roundtable. Your city determines where to meet.
Roundtables are designed for groups of four, with a shared subject and room for everyone to speak. Come for discussion, with no dating expectation.
A friend's $500,000 renovation can make you question whether you should upgrade your own home. Meanwhile, a $100 backpack can leave you agonising over a purchase for weeks. Whether it's a major financial decision or an everyday expense, there's more to being good with money than simply spending less. So how do you make better money decisions without overthinking every dollar? In this episode, Ana catches up with Elliott O'Callahan for the second instalment of his money journey. They explore how small habits, clear goals and a few personal spending rules can make managing money easier. But they also tackle the other side of being financially careful, including knowing when it's actually okay to spend. In this episode we'll discuss: How Elliott approaches short-term spending, saving for his first home and his longer-term FIRE goals. Elliott's experience setting up the First Home Super Saver Scheme and using salary sacrifice to work towards a property deposit. Why a friend's $500,000 renovation prompted Ana to question the opportunity cost of upgrading her own home. What it means to build your own "rich life", and why Elliott values health, music and time with friends more than expensive cars. Why your savings rate is about more than numbers, and how everyday behaviour can make the difference between saving 5% and 50%. How Elliott uses Up Bank to automatically split his pay, and why having a system can remove hundreds of little money decisions. ️ Why Ana once prioritised cheap housing and travel over almost everything else, and how having a family changed her financial goals. ⏳ How the 30/30 rule and five simple questions from minimalism can help put the brakes on impulse purchases. The $100 backpack, expensive barefoot shoes and the surprising mental cost of researching a purchase for too long. The big takeaway? Being 1% better with money isn't about denying yourself everything or making the perfect financial decision every time. It's about understanding what actually matters to you, building habits that support those priorities and recognising when being too careful with money might be costing you something else. @tashinvests (https://www.instagram.com/tashinvests/) @anakresina (https://www.instagram.com/anakresina/) @getrichslowclub (https://www.instagram.com/getrichslowclub/) @pearlerhq (https://www.instagram.com/pearlerhq/) Get Rich Slow Club (https://pearler.com/getrichslowclub) Pearler (https://pearler.com/) YouTube (https://www.youtube.com/@getrichslowclub) Disclaimer: Hosted on Acast.
Episode information is provided by the publisher. Listening takes place on the publisher’s service.
How will you know when you’ve reached true wealth? Is it when you have your dream home? Once you own an expensive car? Perhaps the signifier is when you’re wealthy enough to have your own private airplane? In Tony’s opinion, these are the wrong things to use when measuring your wealth. Uploaded 12-09-19 The people with mansion-sized homes, with three sports cars sitting in the garage, with a private plane that takes them to and from their vacation home – these people may not necessarily have access to true wealth. None of these are indicators of true wealth; they’re indicators of monetary wealth. True wealth is the ability to live life on your own terms. It’s freedom. Tony explains that money itself isn’t wealth, it’s a vehicle – a tool you can use to achieve financial freedom, to go after the dreams you didn’t think were possible, to design your life in a way that makes you feel alive and fulfilled. While Unshakeable is a financial freedom playbook, the process of becoming unshakeable
The Five Pillars of Financial Freedom | Jim Rohn Motivation True financial freedom isn’t just about money—it’s about building the habits, mindset, and principles that create lasting wealth. In this powerful Jim Rohn motivational video, you’ll discover the five essential pillars of financial success that can help you create security, opportunity, and independence. Uploaded 05-10-25 Jim Rohn explains that wealth is not something you chase—it’s something you attract by becoming a disciplined, responsible, and growth-minded individual. These five pillars will show you how to manage your money wisely, invest in yourself, and build a financial foundation that supports the life you want. In this video, you’ll learn: The five pillars of financial freedom and how to apply them. Why discipline is more important than income when building wealth. How to create multiple streams of income for financial security. Why financial freedom starts with self-education and personal growth. Practical steps to
🇺🇸 TWO NAVY SEALS. TWO INCREDIBLE JOURNEYS. ONE POWERFUL MISSION TO TRANSFORM YOUR FINANCIAL FUTURE! Michael Jaco welcomes fellow former Navy SEAL Larry Yatch, founder of TruPath Mastery, for an eye-opening conversation about success, leadership, financial trauma, and the hidden subconscious patterns that can keep even the most accomplished people from reaching their full potential. With 24 years as a Navy SEAL and 11 years as a CIA security operative, Michael shares the powerful lessons of mental discipline, intuition, and personal transformation that shaped his extraordinary journey. Larry brings 10 years of Navy SEAL service and an impressive career advising Fortune 50 executives. But despite achieving tremendous professional success, he discovered that the survival patterns that once made him successful were also keeping him trapped in his own business. THE BIG REVELATION: YOUR MONEY HABITS MAY HAVE VERY LITTLE TO DO WITH MONEY! From childhood programming and fear of scarcity to
An optional overtime shift opens up and you automatically say yes. What is that time buying? The income and the hours you trade both deserve a clear purpose. In this episode of The Level Up Podcast, Paul Alex breaks down how to evaluate a genuinely optional extra shift against your needs, goals, and available time. Paul reflects on long law enforcement weeks and wanting greater control over his time. The episode distinguishes a real choice from required work or income needed for essentials, then asks what the next additional shift serves. There may be a strong reason to take it. Name that reason and consider what the hours would otherwise support, including recovery, a personal commitment, or learning. A deliberate comparison can help you decide without assuming that either money or time should always win. In this episode, you’ll learn: • Why required hours and essential income change the context of the decision. • How to identify the specific need or goal an optional shift serves. • W
Your body doesn't work like you think... Take your personal data back with Incogni. How and when people are having kids is changing, but our bodies aren't. As we get older, it can get harder to have kids when we want to. So smart people figured out it’s possible to remove eggs, freeze them, and unfreeze them to use later. They can even fertilize those eggs to make embryos and freeze those. Basically, humans invented cryosleep! … Just for tiny cells. It’s totally sci-fi - and you need to know about it. This is a level of control over our bodies no species has ever had before. It’s already changing people’s lives - and how our species can reproduce. But there are real concerns about whether it’s worth it. Because let me tell you, the process is not easy. I’ve been taking medication for two weeks. And at the same time, I’ve been doing research, talking to doctors, and learning as much as I can about the cutting edge of fertility tech. In this video, I'm going to take you behind the scenes
What if success isn't something you chase, but something you attract through the person you become? Real success begins with personal growth, self discipline, and the value you bring to the world. Instead of constantly searching for shortcuts or waiting for opportunities, focus on developing the skills, mindset, and character that make meaningful achievements possible. This powerful motivational speech explores timeless principles of success, wealth creation, personal development, and the importance of becoming more valuable to others. Discover why your personal growth influences your results, how daily discipline shapes your future, and why helping others achieve their goals can become one of the most powerful foundations for your own success. In this motivational journey, you'll explore: • The Attraction Principle: Why success is connected to the person you become rather than simply what you pursue. • The Marketplace Rule: How developing valuable skills and contributing to others can
Tash's 2014 Mazda 2 still works, so why is she seriously considering a new Polestar? She's spent months weighing up the extra space, safety features and driving experience against the cost. It's a much bigger version of the same dilemma we face with everyday spending: knowing when to save, when to wait and when spending more might actually make sense. So how do you know when a purchase is worth the money? In this episode, Ana and Tash explore the everyday money moves that shape our financial decisions, from automated investing and forgotten subscriptions to planning major purchases. They also unpack Tash's ongoing Polestar dilemma, comparing different approaches to buying a car, the true cost of ownership and the difference between what we need and what we really want. This episode is sponsored by Polestar. In this episode we'll discuss: ️ How leaving flights until the last minute left Ana facing fares above $600, and why a $25 flight change overseas was such a pleasant surprise. How T
⚠️ Important note: This episode discusses the First Home Super Saver (FHSS) scheme. Some information shared may be outdated or subject to change. Please refer to the Australian Taxation Office (ATO) for the most up-to-date and accurate information on eligibility, contribution limits, tax treatment and withdrawal rules before making any financial decisions. ATO: First Home Super Saver scheme (https://www.ato.gov.au/individuals-and-families/super-for-individuals-and-families/super/withdrawing-and-using-your-super/early-access-to-super/first-home-super-saver-scheme) Saving for a first home is complicated enough without putting part of your deposit into super. But could the potential tax benefits make it worthwhile? Elliott is using the First Home Super Saver scheme to prepare for a home purchase in three to five years. Ana has used it too, even salary sacrificing 100% of her pay for a short period. Together, they explore the benefits, limits and mistakes to watch for when saving through s
Starting a business alongside your full-time job sounds like a sensible way to test an idea without risking your regular income. But what happens when that side business starts making money and growing it means giving up your salary? Emma was earning nearly $100,000 between her job and business, yet going full-time meant potentially dropping back to just $30,000. So how do you give a side business a real chance without sacrificing your financial security or every spare hour you have? In this episode, Emma and Tash share how they built businesses around their existing jobs, studies and personal lives. From squeezing client work into evenings and weekends to navigating tax, burnout and the decision to become fully self-employed, they explore what it actually takes to turn an idea into a business, and whether going full-time should even be the goal. In this episode we'll discuss: Why starting a business doesn't have to mean quitting your job, and why some people are perfectly happy keepin
School policy should consider all families rather than follow the loudest parental voices.
Share your view, then see how readers voted. No sign-in required. This poll is shared across stories.
Do you agree or disagree?
Common Quandary
A Common Quandary to discuss
Another conversation to explore, separate from this news story.
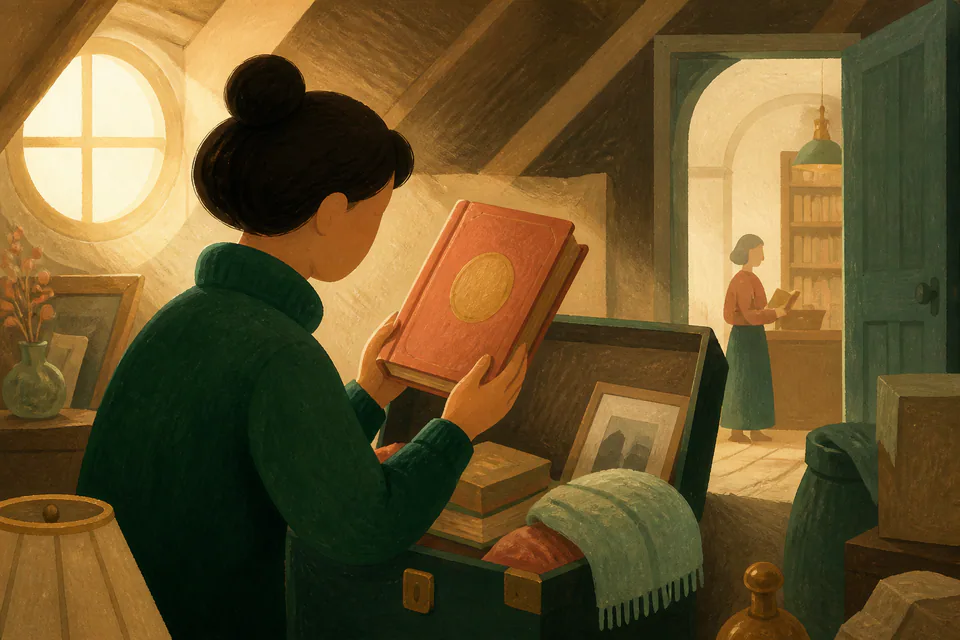
You find a rare library book your father kept for forty years. Do you return it anonymously?
While clearing your father's attic, you find a rare book stamped by the local library and due in 1986. The library would be thrilled to recover it, but returning it openly would expose a secret he apparently kept for decades—and might produce a spectacular overdue fine.
Does making an old wrong right require admitting who did it?